
Insurance automation succeeds when every AI recommendation has a controlled route to a decision, an action, and an auditable record.
Insurance workflow automation uses AI and deterministic rules to move work across intake, underwriting, policy servicing, claims, renewals, and compliance. The practical challenge is not generating an answer. It is deciding what the system may do, when a licensed or authorized person must review it, and how the business recovers when data or integrations fail.
Quick answer
Build insurance workflow automation around one bounded process. Validate incoming data, assign AI a narrow task, apply business and regulatory rules, route high-impact or uncertain cases to the right reviewer, write approved actions to systems of record, and preserve the evidence. Start in recommendation mode, measure overrides and exceptions, then automate only low-risk actions that perform reliably.
What’s in this article?
This guide explains which insurance workflows are good candidates, the controls an AI-enabled process needs, a seven-step implementation method, useful metrics, and common failure points.
Why insurance workflow automation needs controls
Insurance work combines documents, customer communications, risk decisions, payments, deadlines, and regulated records. AI can extract application fields, summarize adjuster notes, classify correspondence, or suggest the next action. It should not silently become the policy authority, final decision maker, or system of record.
The NIST AI Risk Management Framework recommends incorporating trustworthiness into the design, development, use, and evaluation of AI systems. Insurance teams also need to consider applicable state rules and the NAIC model bulletin on insurers’ use of AI systems. Requirements vary by jurisdiction and use case, so legal and compliance teams should validate the final design.
Which insurance workflows should use AI?
| Workflow | Useful AI task | Human or rule-based control |
|---|---|---|
| New business intake | Extract fields and detect missing documents | Validate identity, consent, completeness, and source |
| Underwriting preparation | Summarize submissions and flag inconsistencies | Authorized underwriter owns risk and pricing decisions |
| Policy servicing | Classify requests and draft responses | Confirm authority before changing coverage or records |
| Claims intake | Structure first-notice details and route severity | Escalate injury, fraud, litigation, and low-confidence cases |
| Renewals | Identify missing information and prioritize outreach | Apply approved eligibility and communication rules |
| Compliance review | Find missing evidence and policy deviations | Compliance owner resolves exceptions and signs off |
A strong first use case is high-volume, repetitive, measurable, and reversible. Avoid starting with a process where a wrong automated action could materially change coverage, pricing, eligibility, or claim outcomes without review.
How to build insurance workflow automation with AI
1. Map the current decision path
Record the trigger, required data, roles, systems, handoffs, decision authority, deadlines, exceptions, and completion evidence. Separate the decision itself from the work around it. AI may prepare an underwriting file while the underwriter retains authority.
2. Define one narrow AI task
Choose extraction, classification, summarization, anomaly detection, or drafting. Require a structured output with source references rather than accepting free-form prose. A claim-intake result might include policy number, incident date, loss type, missing fields, confidence, and cited document pages.
3. Standardize inputs and data contracts
Define allowed formats, required fields, validation rules, and ownership for each data element. The ACORD data standards provide industry structures that can reduce inconsistent naming and mapping across insurance systems. Reject or quarantine incomplete inputs instead of asking the model to guess.
4. Add policy and authority gates
Model confidence is not permission. Combine it with deterministic checks for jurisdiction, product, amount, customer status, required evidence, role authority, and prohibited actions. Define which outcomes can proceed automatically and which require underwriting, claims, compliance, or supervisory review.
5. Design the exception queue
Every exception needs an owner, priority, service target, source evidence, and resolution code. Show reviewers why the case was routed and what the AI proposed. Capture corrections so the team can distinguish bad data, model error, unclear policy, and integration failure.
6. Update systems safely
Use supported APIs, idempotent writes, retries, and reconciliation. A successful model response is not a completed workflow if the policy administration or claims platform was never updated. Store the input reference, model and prompt version, rule results, reviewer action, downstream response, and timestamp.
7. Roll out by decision risk
Begin in shadow mode, then recommendation mode, then allow low-risk actions such as requesting missing documents. Expand only after performance is stable across products, locations, and case types. Keep a manual fallback and a way to pause automation quickly.
Insurance AI workflow control model
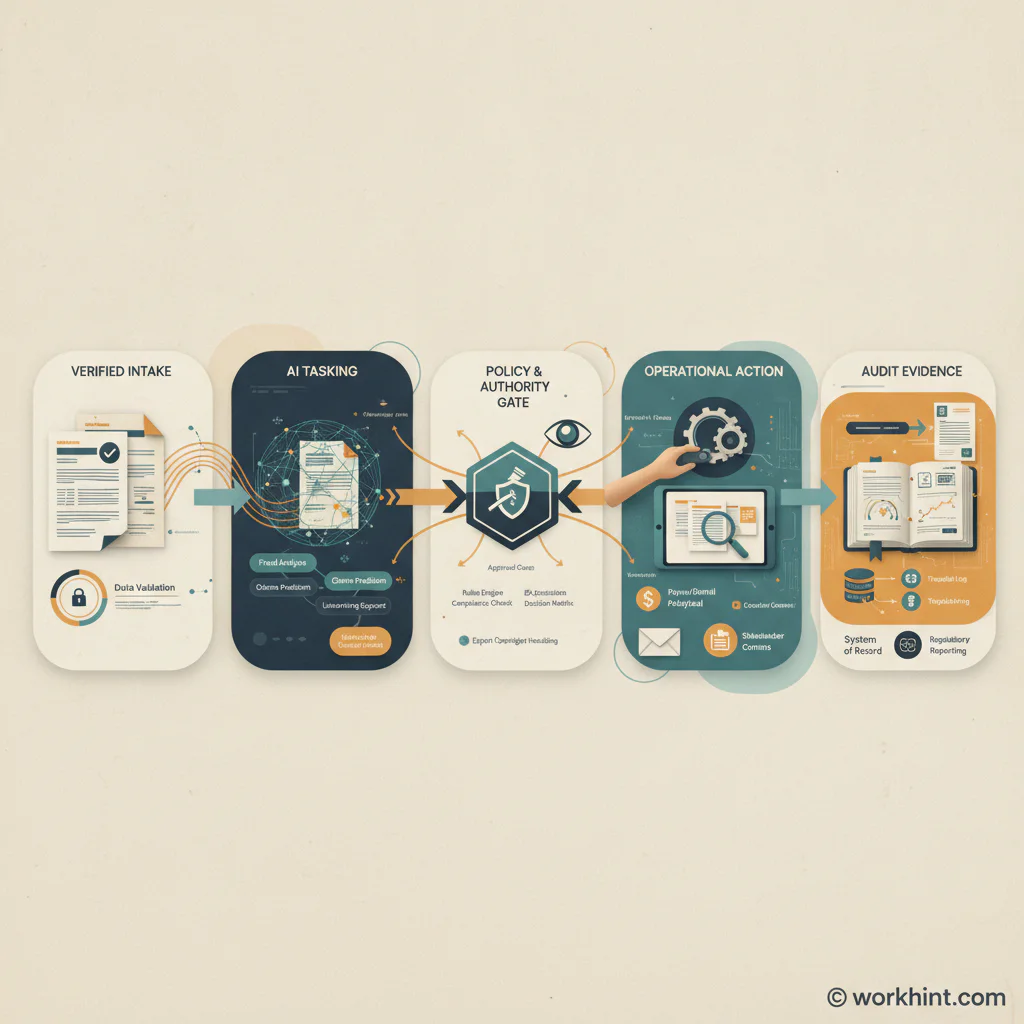
- Intake: authenticate the source and validate required information.
- AI task: extract, classify, summarize, detect, or draft.
- Control gate: evaluate confidence, policy, authority, and impact.
- Review: send uncertain or high-impact cases to the correct role.
- Action: assign work, request evidence, notify, or update a system.
- Reconcile: confirm that downstream records match the approved action.
- Audit: retain evidence, decisions, overrides, and exceptions.
What should insurance teams measure?
- Flow: cycle time, queue age, throughput, and handoff delay.
- Quality: extraction accuracy, false routing, rework, and duplicate actions.
- Human review: override rate, disagreement reason, and review time.
- Reliability: failed integrations, retries, reconciliation gaps, and fallback use.
- Business: cost per case, response time, abandonment, and service-level attainment.
- Governance: access violations, missing evidence, audit completeness, and incident count.
Compare results by workflow stage and case segment. A low average error rate can hide poor performance on one product, document type, or jurisdiction.
Common implementation mistakes
- Automating a broken process before clarifying ownership and rules.
- Letting model confidence substitute for business authority.
- Sending every exception to one generic inbox.
- Measuring model accuracy but not completed and reconciled work.
- Giving an agent broad write access across policy and claims systems.
- Scaling before testing overrides, edge cases, and manual fallback.
Where Workhint fits
Workhint fits in the orchestration layer around insurance AI. A specialist model can analyze a submission or claim; Workhint can help an organization build the configurable work system that controls intake, roles, permissions, assignments, approvals, documents, schedules, escalations, reporting, and automation.
For example, an insurer could connect an approved extraction model to Workhint’s workflow automation platform, route incomplete submissions to an operations queue, assign high-impact cases to authorized reviewers, track service targets, and retain the decision trail. Workhint is not the underwriting model or policy system; it coordinates the work around them.
FAQ
What is insurance workflow automation?
It is the coordinated use of rules, integrations, and sometimes AI to move insurance work from intake through review, action, reconciliation, and audit.
Which insurance process should be automated first?
Start with a high-volume, low-risk process with clear rules, reliable inputs, measurable delays, and a safe human fallback, such as document completeness review.
Can AI make underwriting or claims decisions automatically?
That depends on the decision, jurisdiction, product, controls, and delegated authority. High-impact decisions should receive appropriate human, legal, and compliance review.
How do insurers keep AI workflows auditable?
Record source inputs, model and prompt versions, structured outputs, rule results, reviewer actions, overrides, downstream updates, and timestamps.
How should an insurer evaluate automation vendors?
Assess task fit, data handling, role-based access, integration methods, logging, exception management, monitoring, failure behavior, portability, and contract terms.
Conclusion
Insurance workflow automation works when AI is one controlled component of a complete operating process. Map decision rights, constrain the model’s task, standardize data, add policy gates, design owned exceptions, reconcile system updates, and expand by risk. That approach improves speed without losing accountability.
Leave a Reply