
An expense reimbursement workflow should answer one question before money moves: is this a documented, authorized business expense under the organization’s policy? A workable process captures the claim and evidence, checks it against policy, sends exceptions to an accountable reviewer, and keeps approval separate from payment release.
Make reimbursement approvals easier to follow
Map requests, evidence, review stages, and handoffs in a connected work system.
Quick answer
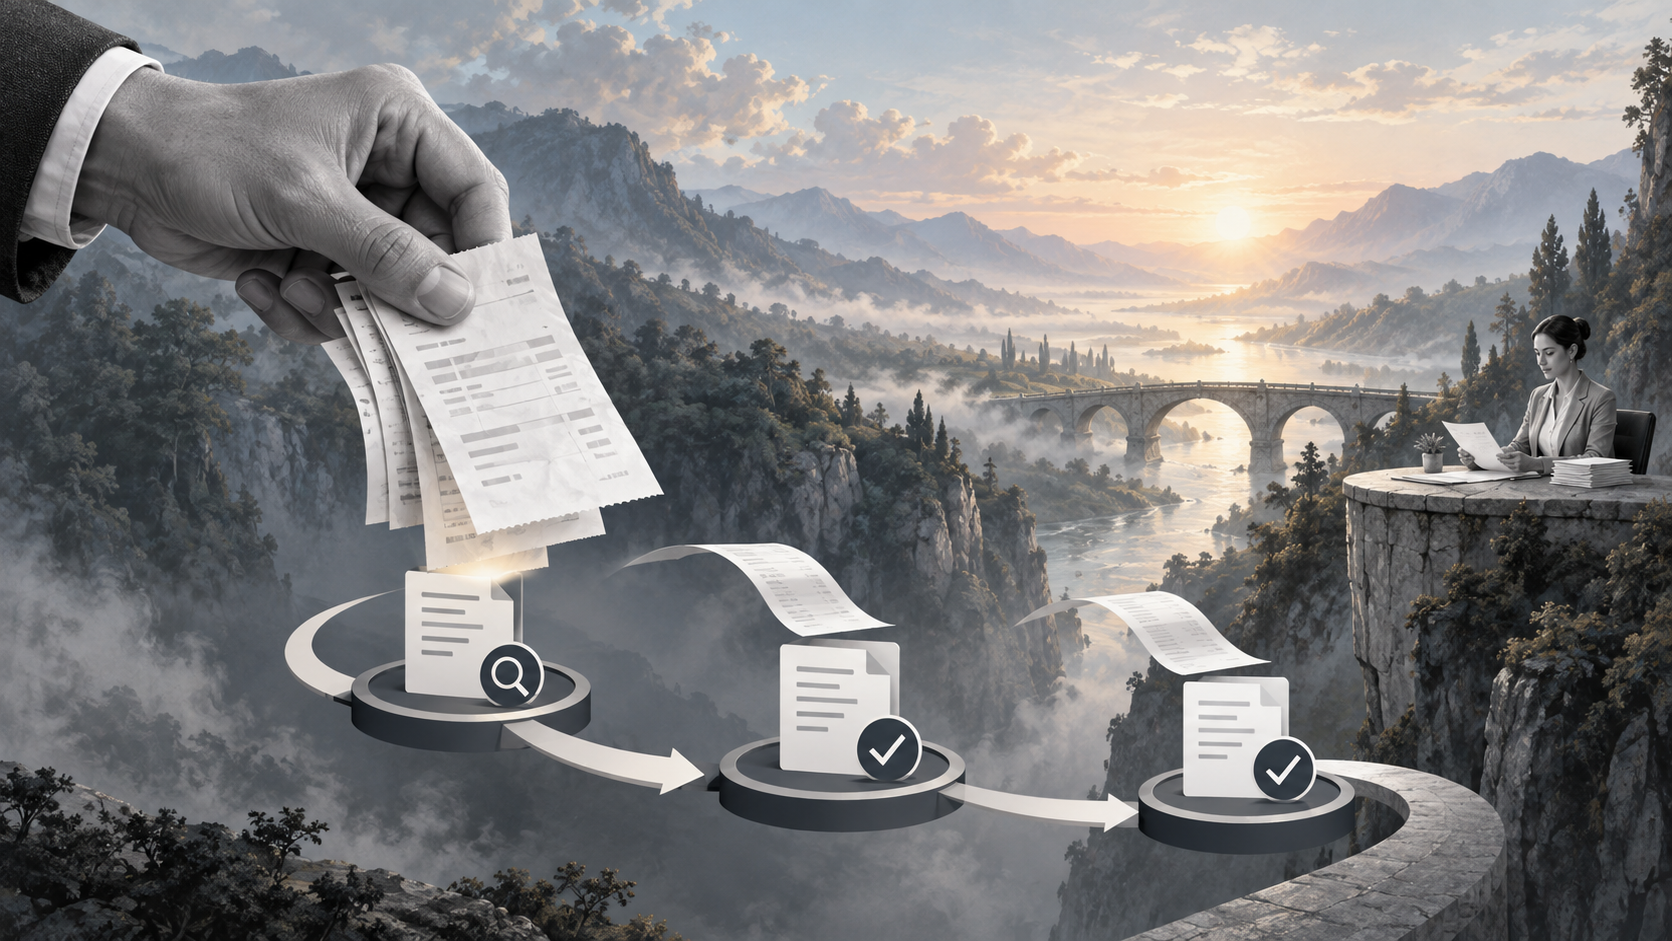
Route each claim through Draft → Submitted → Validated → Approved or Returned → Scheduled → Paid → Reconciled → Closed. Require the receipt and business purpose before approval, assign policy exceptions to a designated reviewer, retain the decision and evidence, and do not let a corrected claim resume at payment without the approval your policy requires.
Define the operating boundary
This article describes a recommended internal control workflow, not tax or legal advice. In the United States, the IRS describes substantiation requirements for business expenses and distinguishes accountable-plan reimbursements in Publication 463 and Publication 15. Your policy, contracts, local rules, and payroll or accounting configuration determine the actual treatment.
Use this workflow for employee or contractor claims where an authorized person reimburses a documented out-of-pocket expense. Do not use it to disguise compensation, to override spending authority, or to substitute for a vendor invoice process.
The reimbursement workflow
- Submit. The claimant enters date, amount, currency, merchant, category, business purpose, cost center or client, and attaches the receipt or other required evidence.
- Validate. The system or reviewer checks required fields, duplicate indicators, policy limits, and whether the claim belongs in reimbursement rather than accounts payable or payroll.
- Review. The manager confirms the business purpose and budget owner reviews charges that need budget approval. A finance reviewer checks documentation and coding.
- Handle exceptions. Missing receipts, late claims, out-of-policy amounts, and unclear business purpose move to Returned or Exception review; they are not silently approved.
- Authorize and schedule. After all required approvals, finance marks the claim payable and schedules it in the organization’s approved payment process.
- Pay and reconcile. Record the payment reference, match the payment to the approved claim, investigate failures or reversals, and close only after the financial record is reconciled.
Approval and evidence matrix
| Stage | Owner | Required evidence | Control and next state |
|---|---|---|---|
| Submission | Claimant | Receipt, purpose, coding | Required fields; Submitted or Draft |
| Business review | Manager/budget owner | Business need and spend authority | Approve, return, or decline |
| Policy review | Finance reviewer | Receipt, category, exception rationale | Validate or send to exception review |
| Payment release | Authorized finance role | Completed approval record and payable amount | Schedule or hold |
| Reconciliation | Finance/accounting | Payment reference and claim ID | Close or investigate difference |
Worked example: a corrected claim
A field supervisor submits a $420 hotel claim with a receipt but no client or project reference. The manager can confirm the trip was required, but finance returns the claim because the coding needed for the expense record is absent. The claimant adds the project and business purpose. The return changes the evidence, so the claim re-enters policy validation and any required approval—not payment scheduling. Once approved, the payment reference is attached to the same claim and accounting reconciles the $420 payment before closure.
Make exceptions recoverable
Every exception needs a reason, owner, deadline, and state. For example, a lost receipt might require an attestation under company policy; a personal charge should be declined; a charge above policy may need a documented exception from the authorized owner. The Committee of Sponsoring Organizations (COSO) frames effective internal control around objectives, risk, control activities, information, and monitoring; its Internal Control—Integrated Framework guidance is useful background for designing—not dictating—your controls.
Where Workhint fits
Workhint can help teams structure the reimbursement intake, collect supporting documents, route claims by category or amount, assign reviewers, record approval outcomes, and show the handoff from approval to payment and reconciliation. Payment execution, accounting treatment, and final authorization stay with the responsible people and systems.
If requests and receipts are scattered across email, spreadsheets, and chat, explore Workhint’s workflow automation approach to map the roles, data, conditions, and status changes around your process.
FAQ
Who should approve an expense reimbursement?
Set approval roles in your policy. A common design separates the claimant, the person confirming business purpose, the person checking policy or coding, and the person authorized to release payment.
Can a claim be paid without a receipt?
Only if your documented policy allows an alternative evidence path and the designated reviewer approves it. IRS guidance may be relevant for U.S. tax treatment, but it does not replace your organization’s policy.
What happens after a reimbursement is returned?
The claimant corrects the missing or inaccurate information. The workflow should preserve the return reason and route the corrected claim back through the required validation and approval steps.
Build a controlled reimbursement path
Start with one clear rule: no payment-ready claim without evidence, ownership, and the approvals your policy requires. Book a Workhint demo to map a reimbursement workflow around your real request, review, and handoff process.
Leave a Reply