
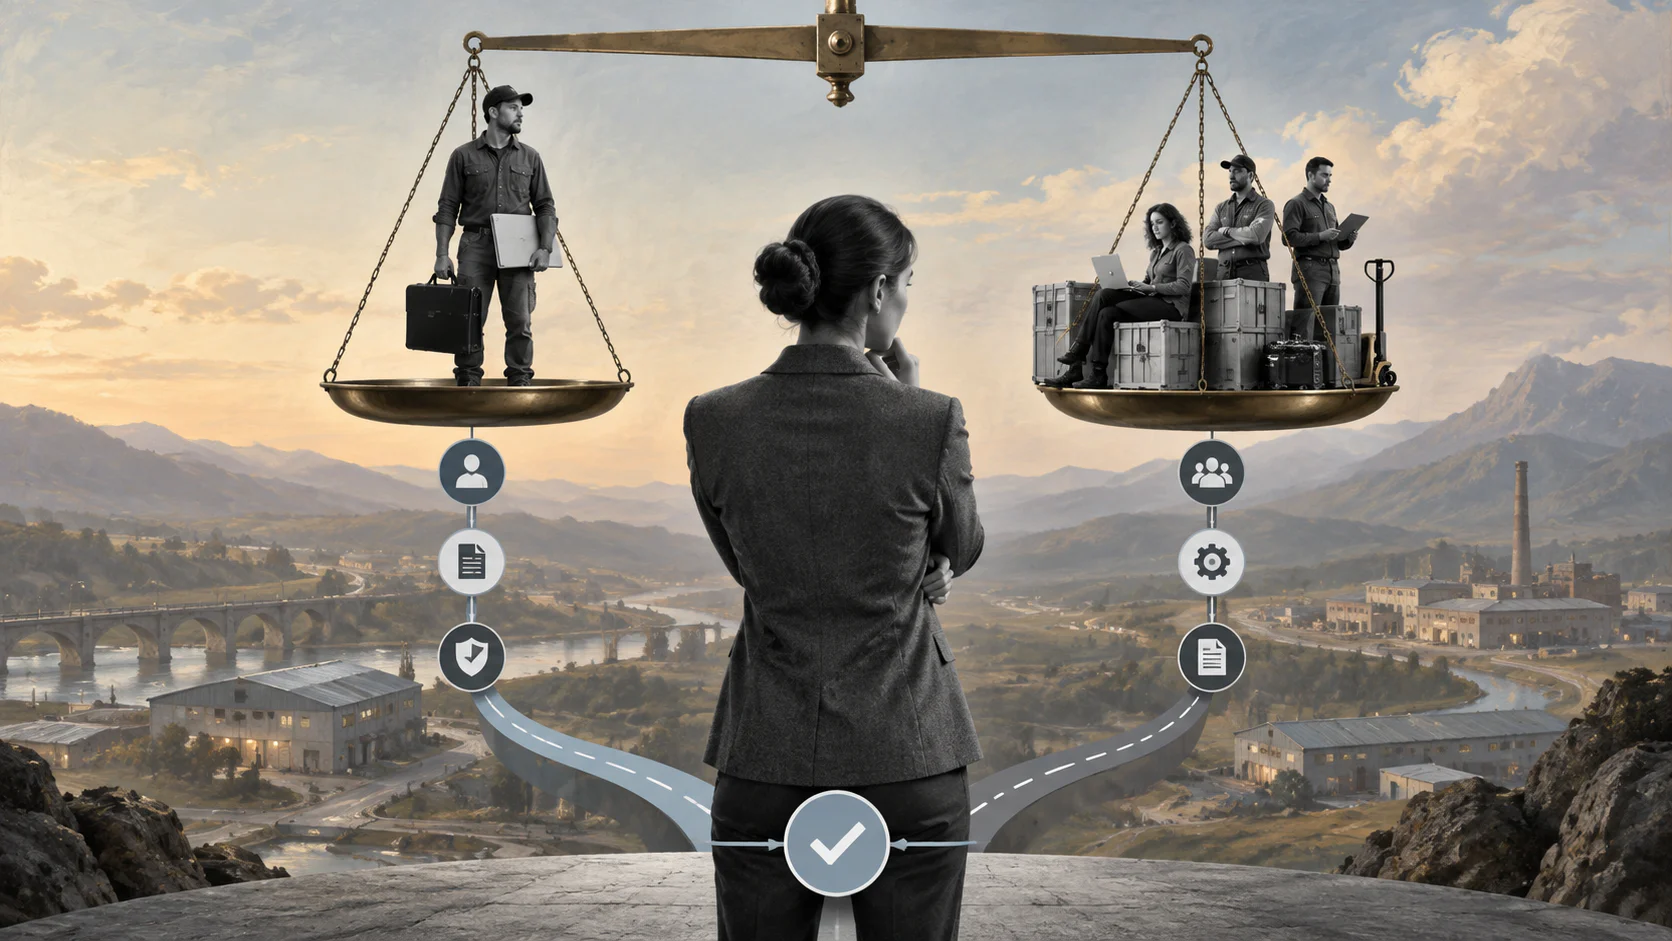
Choosing the wrong engagement path creates duplicated onboarding, unclear ownership, and invoices nobody can approve confidently.
Vendor vs contractor sounds like a terminology question, but the distinction changes how a business approves, onboards, manages, and pays external work. A contractor is usually engaged to perform defined work. A vendor is a broader supplier relationship that may provide products, services, technology, or an entire team.
Quick answer
A contractor typically performs work under a direct agreement, often as an individual or specialized firm. A vendor supplies goods or services through a commercial relationship that may cover many users, locations, orders, or workers. The categories can overlap, so businesses should route each engagement by scope, control, access, risk, invoice structure, and responsible owner rather than relying on the label alone.
What’s in this article?
- The practical differences between a vendor and contractor.
- A comparison table for procurement, operations, HR, and finance.
- A six-step workflow for choosing the right engagement path.
- Common mistakes in onboarding, access, and invoice approval.
Why vendor vs contractor matters
The relationship determines which controls should apply. A freelance designer may need a statement of work, limited file access, milestone acceptance, and a direct invoice path. A design agency may need vendor due diligence, insurance, security review, purchase orders, service levels, and a relationship owner. Both perform external work, but they create different operational dependencies.
The terms are not universal legal categories. In U.S. tax administration, the IRS focuses on behavioral control, financial control, and the relationship of the parties when distinguishing an independent contractor from an employee. Procurement teams may use vendor, supplier, and contractor differently. Define the operating model in the agreement and workflow instead of assuming the name settles it.
Vendor vs contractor comparison
| Decision area | Contractor | Vendor |
|---|---|---|
| Typical relationship | Performs defined work or provides specialized expertise | Supplies products, services, subscriptions, or managed capacity |
| Common form | Individual, freelancer, consultant, or specialist firm | Company, agency, supplier, platform, or service provider |
| Scope | Project, deliverable, assignment, or period of work | Purchase category, service portfolio, recurring supply, or master relationship |
| Operational owner | Hiring manager or project owner | Vendor manager, procurement, or business relationship owner |
| Payment trigger | Approved time, milestone, or deliverable | Purchase order, accepted goods, service period, usage, or SLA |
| Main risk | Worker classification, access, scope drift, and supervision | Supply continuity, security, concentration, service failure, and commercial exposure |
How to choose the right engagement path
1. Define what the business is buying
Start with the outcome. Are you buying one person’s work, a defined project, a managed service, a recurring subscription, physical goods, or capacity from a supplier team? This first distinction shapes every later approval.
2. Identify who controls delivery
If an internal manager assigns work directly to an individual, reviews their deliverables, and controls access, the relationship needs contractor-specific scrutiny. If a company manages its own staff and commits to service levels or outcomes, a vendor path may fit better. Labels do not override how the relationship operates.
3. Match due diligence to the risk
Contractor review may emphasize identity, classification, agreement terms, tax documentation, credentials, insurance, and system access. Vendor due diligence may also cover financial stability, security, privacy, subcontractors, business continuity, sanctions, insurance, and concentration risk. NIST’s Cybersecurity Supply Chain Risk Management guidance provides a useful framework for managing supplier risk across the lifecycle.
4. Use the right agreement structure
A contractor may work under an independent contractor agreement plus a statement of work. A vendor relationship may use a master services agreement, purchase orders, data-processing terms, service levels, order forms, and individual SOWs. Keep scope, acceptance, change control, pricing, confidentiality, intellectual property, and termination rules aligned.
5. Design access around the work
Grant the minimum systems, data, facilities, and customer information required. Record the access owner and expiration date. The NIST access-control catalog supports account management and least-privilege practices that are useful for both individual contractors and vendor teams.
6. Connect acceptance to payment
Finance needs an evidence path. Contractor invoices may depend on approved hours or accepted milestones. Vendor invoices may require a valid purchase order, receipt, service-period confirmation, usage record, or SLA review. Every invoice should point to the agreement, business owner, budget, acceptance event, and exception path.
Use a routing workflow before work starts
- Capture the business need, scope, duration, location, budget, and access requirements.
- Decide whether the counterparty is an individual, specialist firm, agency, supplier, or platform.
- Route classification, procurement, legal, security, finance, and insurance reviews based on risk.
- Approve the agreement, scope, rate or pricing schedule, and payment trigger.
- Release access and work only after required records are complete.
- Review performance, renewals, invoices, access, and risk on a defined cadence.
- Close the engagement by removing access, resolving invoices, and retaining required records.
Common mistakes
- Using vendor and contractor interchangeably. This can send an individual through a corporate supplier process or skip vendor risk review for a critical service provider.
- Letting the requester choose the classification alone. The requester should describe the work; the right control owners should select the path.
- Using one generic onboarding checklist. A low-risk specialist and a vendor processing customer data should not receive identical reviews.
- Ignoring subcontractors. A vendor may rely on other firms or workers who also need appropriate controls.
- Approving invoices without delivery evidence. The invoice should match accepted work, received goods, or a verified service period.
- Forgetting offboarding. Access, equipment, documents, renewals, open orders, and final payments need named owners.
Where Workhint fits
Workhint can turn the vendor-versus-contractor decision into a repeatable intake and routing system. Teams can capture the request, identify the engagement model, route reviews, collect agreements and documents, assign role-based access, track work or service delivery, approve invoices, monitor renewals, and coordinate closeout.
For organizations comparing a vendor management platform, the practical requirement is not only a supplier directory. The system should apply the correct workflow to individuals, agencies, service providers, and suppliers while preserving ownership and an audit trail. Contractor-heavy teams can also connect this structure to contractor management workflows for classification, onboarding, assignments, and access.
Frequently asked questions
Is every contractor a vendor?
Some accounting or procurement systems record contractors as vendors because they receive payments. Operationally, however, an individual contractor may need worker-specific classification, onboarding, access, and supervision controls that do not apply to an ordinary supplier.
Can a vendor also provide contractors?
Yes. Staffing firms, consultancies, and managed service providers may supply people who work inside a client’s environment. The business should govern both the vendor relationship and the individual worker’s assignment, access, safety, and offboarding.
What tax form does a contractor or vendor provide?
U.S. requirements depend on entity type, location, payment type, and other facts. Businesses commonly collect Form W-9 from U.S. payees and an appropriate Form W-8 from certain foreign payees, but finance or tax advisors should confirm the correct documentation.
Who should own vendor and contractor records?
Ownership is usually shared. Procurement owns the commercial supplier relationship, the business owner owns the need and acceptance, HR or legal may review classification, security owns access risk, and finance owns payment controls. One system should show each accountable owner.
Conclusion
The useful distinction in vendor vs contractor is not the label; it is the operating model. Define what the business is buying, who controls delivery, which risks apply, how access is granted, and what triggers payment. Then route the engagement through the right approval, onboarding, review, and closeout workflow before work begins.
Leave a Reply